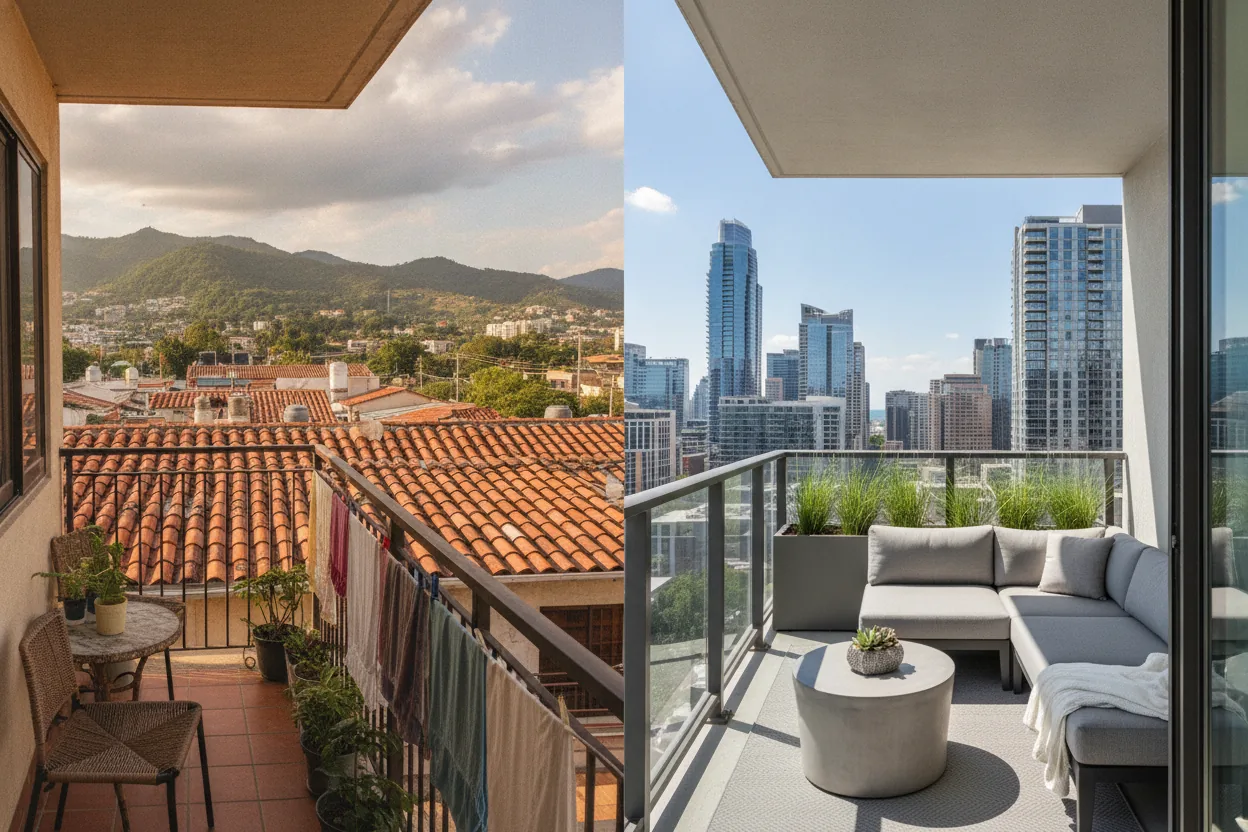
A one bedroom in Pitillal reportedly rents for well under what similar square footage costs a few miles away in Zona Romántica. So why does the same city produce two completely different price worlds for the same size apartment, and which one are you actually going to end up paying for? That gap is the question most relocation guides skip right past. It's the question this post actually works through.
The core mechanism is simple enough. Rent, labor, and local goods in Puerto Vallarta are priced in pesos, while a remote salary or US pension arrives in dollars. That spread is real money, no argument there. But it doesn't spread evenly across every expense category, and the categories where it breaks down are exactly the ones that decide whether this move saves you money over five years or just defers a bigger bill down the road.
Who actually benefits from the gap? Mostly the person who already has dollar income and zero dependency on Mexico's public systems. Who absorbs the risk? Anyone who budgets Puerto Vallarta like a slightly cheaper version of home, rather than treating it as a different financial system with its own failure modes. The three sections below take that risk apart category by category: rent, the broader monthly budget, and healthcare. Each one distributes the gap differently, and you need to understand all three.
Puerto Vallarta Rent Looks Cheap, But The Zip Code Decides The Real Price
Most newcomers assume a one bedroom in Puerto Vallarta is a single price point they can budget against. The numbers say otherwise. The spread between a Pitillal studio and a Zona Romántica high rise with a pool isn't a rounding error, it can run to a large multiple on identical square footage, and that multiple exists because the two neighborhoods are selling completely different products.
Same City, Two Rent Worlds
One Bedroom, Same Square Footage
Pitillal
LOW
Priced to local peso wages
Zona Romantica
HIGH
Priced to dollar demand, near Miami Brickell levels
The gap is driven by who the market serves: local labor vs. dollar denominated remote workers, retirees, and investors.
Source: Source: Article estimates, Puerto Vallarta neighborhood rent comparison
Pitillal and the areas off the hills around 5 de Diciembre rent to a local labor market. Service workers, shop owners, families who've lived there for generations, wages set in pesos. A studio there reflects what that local economy can actually sustain, which runs well below what the expat corridor commands. Versalles, Zona Romántica, and the Marina serve a different market entirely, one pricing against demand that includes US and Canadian remote workers, retirees converting dollar pensions, and short term capital treating a condo as both a residence and an investment vehicle.
That second market is why rents in the expat corridor climb well above local levels, and larger units in amenity heavy buildings with gyms and pools stack a further premium on top. The ceiling on that range can approach what a one bedroom costs in parts of Miami's Brickell district. Puerto Vallarta didn't get expensive in those zones by accident. Dollar denominated demand bid up a fixed supply of waterfront and walkable inventory, the same mechanism that reprices any coastal city once outside capital finds it.
So Puerto Vallarta rent as a single number is close to meaningless. What actually matters is which few square kilometers you're willing to live in, because that choice alone can double or triple the biggest line item in your budget. Disciplined expats who stay away from the postcard neighborhoods capture most of the arbitrage. Everyone else pays Miami adjacent rent for the privilege of a Mexican grocery bill around it.
Why the Peso to Dollar Gap Exists
Step 1. Rent, labor, and local goods are priced in pesos
Step 2. Remote salary or US pension arrives in dollars
Step 3. Dollar demand bids up fixed waterfront and walkable inventory
Step 4. Expat corridor rents climb far above local levels
Step 5. Disciplined expats avoiding postcard zones capture the arbitrage
Source: Source: Article analysis of currency and pricing mechanics
Puerto Vallarta Budget Tiers Look Tidy, But Inflation Hits Each Category Differently
Rent is the line item that swings most by neighborhood, but it's only one entry in a much larger monthly budget, and the other entries don't move together. Relocation guides love sketching out a few rough budget tiers, from bare bones single living up through a comfortable couple or small family setup. Those numbers work fine as a rough starting map. Treat any specific dollar figure attached to them with real skepticism, though, because the categories inside those tiers move at different speeds, and the published tier won't tell you which ones are drifting.
Rent and groceries, the two line items everyone fixates on, are also the two most exposed to currency swings. The peso has at times strengthened meaningfully against the dollar in recent years, and when that happens, a grocery bill quoted in pesos quietly gets more expensive in dollar terms even while nothing on the shelf changes price. Anyone budgeting off an old article is working from a different exchange rate environment than the one they'll actually live in. Worth flagging, not ignoring.
Eating out tells a different story. A modest monthly eating out budget at the low tier, rising at the family tier, reflects a labor cost structure, restaurant staff wages, that hasn't repriced anywhere near as fast as real estate. This part of the arbitrage tends to hold up longest, since it depends on local wage levels rather than asset prices chasing foreign capital.
Two Rental Markets, Different Buyers
| Factor | Pitillal / 5 de Diciembre | Zona Romantica / Marina |
|---|---|---|
| Buyer base | Local service workers, families | US/Canada remote workers, retirees, investors |
| Currency behind demand | Pesos | Dollars |
| Price driver | Local wage sustainability | Outside capital and amenity premium |
| Relative rent level | Low | Approaches Miami Brickell |
Source: Source: Article comparison of Puerto Vallarta rental zones
Where the budgets get genuinely fragile is the extras, schooling, and activities lines. These categories are often placeholders for costs that don't scale linearly: private school tuition for a family moving with kids, or a membership at an international clinic that only reveals its real price once you actually need it. A budget that balances neatly on a spreadsheet can fail quietly in year two if either of those categories got underestimated at the outset.
The published ranges are a reasonable starting map, nothing more. They favor the household that treats healthcare and schooling as negotiated contracts to shop around, not fixed costs to accept at face value. Everyone else inherits the gap between the spreadsheet and the actual bill. Healthcare is the category most likely to break that spreadsheet, and it runs on a different logic entirely.
Puerto Vallarta Healthcare Follows A Different Logic Than Everything Else On The List
Most relocation content treats healthcare as a line item roughly comparable to groceries: a monthly number you plug in and move on. That framing undersells how differently healthcare risk is structured in Mexico compared to the US employer insurance model most American movers grew up with.
Who Benefits vs Who Absorbs the Risk
| Profile | Benefits From Gap | Exposed To Risk |
|---|---|---|
| Dollar income, no local dependency | High | Low |
| Budgets Mexico like "cheaper home" | Low | High |
| Lives in postcard neighborhoods | Moderate | Moderate to High |
| Relies on Mexico public systems | Low | High |
Source: Source: Article analysis of relocation risk distribution
What actually happens, and this matches how expat communities in Puerto Vallarta operate day to day, is a split system. Routine and everyday treatment gets paid out of pocket directly to doctors and clinics, while private or international insurance sits in reserve specifically for emergencies or major procedures. That's close to the inverse of the US system, where insurance is expected to cover routine visits and the out of pocket exposure concentrates at the catastrophic end.
That split exists because out of pocket private care in Puerto Vallarta is priced against local costs, not US billing codes, which makes a routine consultation, bloodwork, or minor procedure cheap enough that insuring against it just isn't worth the premium. A specialist visit that would cost noticeably more in the US frequently costs a fraction of that paid directly in Mexico. International or private insurance only pays for itself when the bill gets large enough that a payment plan or savings account can't absorb it: surgery, hospitalization, a cancer diagnosis.
The risk this structure creates isn't catastrophic cost, it's underinsurance at the margins. Someone skips the international policy entirely because the out of pocket visits feel so manageable, then discovers that emergency coverage, when they actually need it, has exclusions, waiting periods, or network limitations nobody mentioned at signup. The expat who wins here treats the insurance decision as its own research project, separate from the monthly budget exercise, and reads the policy for what it excludes rather than what it advertises covering.
Key Facts: The Mechanics Behind the Gap
| Insight | Why It Matters |
|---|---|
| Rent is not one number | Neighborhood choice alone can double or triple the biggest line item in the budget |
| Inflation hits categories unevenly | Published budget tiers do not reveal which categories drift fastest |
| Healthcare is a separate system | Requires its own planning, not a simple cheaper substitute for US coverage |
| Five year horizon matters | Decides whether the move saves money or just defers a bigger bill |
Source: Source: Article summary, Puerto Vallarta vs Austin cost of living discussion
Puerto Vallarta's healthcare arbitrage is real, and for most routine years it'll outperform a US insurance premium by a wide margin. But this is the one category in these budgets where a bad decision doesn't show up as a slightly bigger grocery bill. It shows up as a six figure medical evacuation claim denied on a technicality. That asymmetry deserves far more attention than its modest monthly placeholder in most budgets suggests, and it's also the answer to the question this post opened with: the gap between the cheap number and the real number isn't one spread. It's three, in rent, in which budget categories drift, and in how healthcare risk is structured, and the move only saves money for someone who prices all three rather than just the first one they see.
This article is for informational and educational purposes only and does not constitute financial, investment, or legal advice. The views expressed are analytical observations and should not be relied upon for personal financial decisions. Always consult a qualified financial advisor before making investment decisions.